 ultimate-guide
Buying Coastal Homes in California: A 2026 Guide
Table of Contents
- Understanding the Coastal Real Estate Market
- Top Coastal Regions and Beach Towns to Consider
- Coastal Home Buying Checklist: What to Evaluate Before Making an Offer
- Flood Risk for Coastal Homes: Assessment and Due Diligence
- Coastal Home Inspection: Critical Areas and Red Flags
- Coastal Property Insurance: Coverage, Costs, and Planning
- Total Cost of Ownership and Long-Term Financial Planning
- Your Next Steps: Finding the Right Coastal Home
- Frequently Asked Questions
Last Updated: October 11, 2026
Understanding the Coastal Real Estate Market
Buying coastal homes in California requires understanding how oceanfront location, environmental exposure, and regulatory frameworks shape both value and long-term costs. Coastal location commands premium pricing, but that premium carries hidden obligations.
Coastal properties face specific risks, erosion, flood exposure, insurance volatility, and strict building codes, requiring higher maintenance costs, specialized insurance, and ongoing due diligence across decades of ownership.
Top Coastal Regions and Beach Towns to Consider
When buying coastal homes in California, location within the state matters enormously for price, inventory, and market dynamics. Understanding regional price tiers helps you identify where your budget aligns with available inventory.
Northern California Coastal Markets
Northern coastal communities including Half Moon Bay, Santa Cruz, and Mendocino County offer lower entry prices than Southern California. Half Moon Bay properties typically range from $1.2 million to $3 million; Santa Cruz averages $1.5 million to $2.8 million. These markets attract primary-residence buyers and second-home purchasers seeking less-crowded alternatives, with slower inventory turnover providing more negotiating leverage.
Central Coast Markets
Central Coast communities including Carmel-by-the-Sea and Cambria represent a middle tier between Northern and Southern California pricing. Carmel oceanfront properties range from $3 million to $8 million; Cambria offers $800,000 to $2.5 million. Limited year-round inventory supports stable pricing but creates competitive bidding situations.
Southern California Coastal Markets
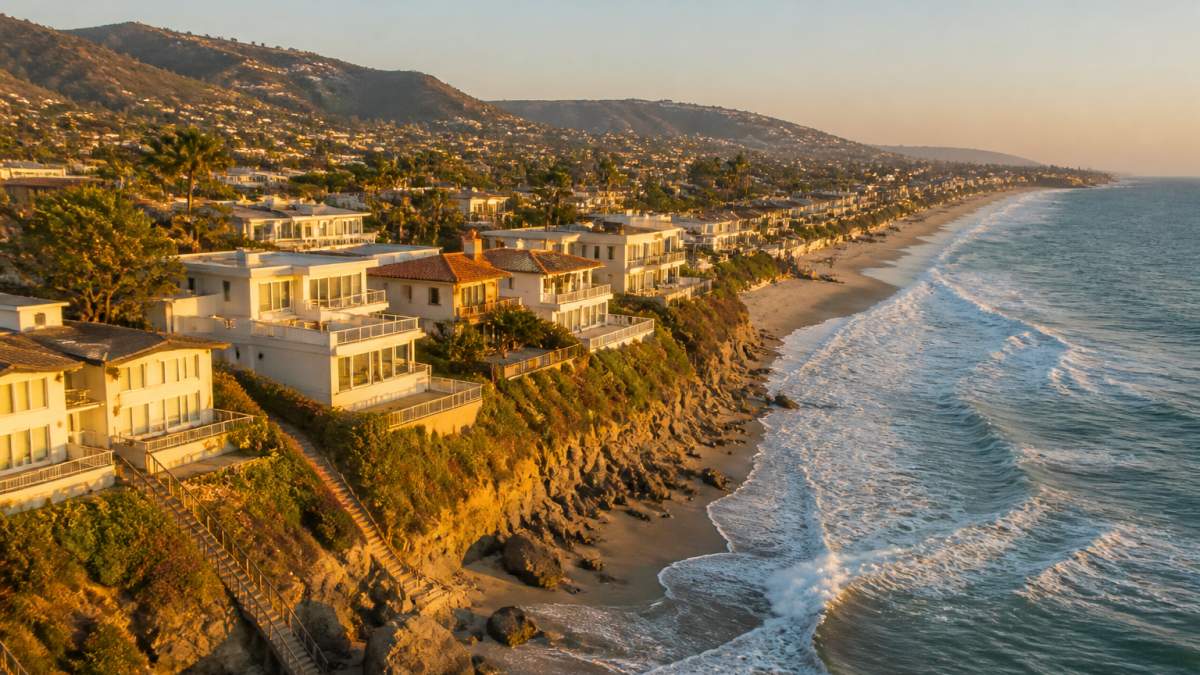
Southern California contains the state's most active and expensive coastal markets. Orange County ranges from $2 million to $10 million; Malibu frequently exceeds $8 million; San Diego County ranges from $1.5 million to $5 million. Southern California coastal markets show the highest inventory turnover, most active buyer competition, and strongest appreciation trends.
Regional Comparison Framework
Northern California coastal markets feature smaller communities with strong environmental protection; Central Coast markets balance amenities with cultural identity; Southern California markets offer robust services but face higher competition and faster appreciation.
Southern California coastal properties list year-round with spring peaks; Central Coast and Northern California show pronounced seasonal patterns with concentrated spring listings.
Lifestyle and Community Characteristics
Each coastal region attracts different buyer profiles: Laguna Beach appeals to artistic buyers; Newport Beach to yacht club members; Carlsbad and Encinitas to families; Carmel to cultural enthusiasts; Half Moon Bay and Santa Cruz to younger buyers and remote workers.
Your regional choice should reflect lifestyle priorities, career location, family needs, and appreciation expectations, as equivalent-priced properties vary dramatically across regions.
Coastal Home Buying Checklist: What to Evaluate Before Making an Offer
Buying a coastal home involves more moving parts than standard purchases. A structured process, property evaluation, due diligence, inspection, and closing coordination, protects your interests.
Phase 1: Pre-Offer Property Evaluation
Before making an offer, review the property's flood zone status using the FEMA flood map tool at fema.gov.
Research local zoning and coastal regulations through the planning department. Confirm setback requirements, height restrictions, and coastal commission overlay zones.
Review public records for property history, previous sales, and assessed values. Search for recorded easements, covenants, and restrictions.
If applicable, request the HOA's architectural guidelines, reserve study, and meeting minutes.
Assess view obstruction potential by reviewing zoning for adjacent parcels. Confirm height restrictions and setback requirements, as a current ocean view does not guarantee permanence.
Phase 2: Making an Offer with Contingencies
Structure your offer with financing, appraisal, and home inspection contingencies (10-14 days).
Include a coastal-specific due diligence contingency allowing 7-10 days to obtain flood insurance quotes, verify coastal commission compliance, and review specialized inspection findings.
Make your offer contingent on satisfactory resolution of all due diligence items.
Phase 3: Post-Offer Due Diligence (7-14 Days)
After your offer is accepted, request insurance quotes from at least three providers. Ask about flood insurance availability, coverage limits, and annual premiums.
Schedule a specialized coastal home inspection with documented oceanfront experience in your region. Coastal inspections typically cost $600-$1,200 and take 3-4 hours.
Obtain the official FEMA flood map and request historical flood records from county emergency management.
Review the title report carefully for easements, covenants, and restrictions. Confirm public beach access easements and understand exactly what rights they grant.
Phase 4: Inspection and Structural Evaluation (Days 8-14)
Hire a specialized coastal home inspector.
Focus on foundation and structural elements. Coastal soils vary, clay soils move during wet periods; sandy soils shift unevenly.
Evaluate roof and exterior cladding for salt spray damage. Metal components corrode faster in coastal environments.
Inspect windows, doors, and weatherproofing carefully. Water stains, soft drywall, and mold indicate moisture problems.
Have the inspector evaluate drainage and grading. Ask about the property's drainage history and whether current grading adequately protects the foundation.
Phase 5: Final Walkthrough and Closing Coordination (Days 15-30)
Schedule a final walkthrough 24-48 hours before closing. Confirm agreed-upon repairs are complete and personal property included in the sale remains in place.
Coordinate with your lender to finalize financing. Provide proof of homeowners and flood insurance. Confirm down payment and closing costs with your title company.
Review the final closing disclosure 3 business days before closing. Verify loan terms, interest rates, closing costs, property taxes, insurance, and HOA fees match your estimates.
Flood Risk for Coastal Homes: Assessment and Due Diligence
Flood risk represents one of the most critical due diligence items. Federal flood maps categorize properties into zones based on historical data and storm surge modeling. High-risk zones (AE or VE) require flood insurance; unmapped properties can still flood during extreme events.
Request the official FEMA flood map. Unmapped does not mean risk-free; many properties that flooded recently were in unmapped areas.
Evaluate storm surge models from NOAA for hurricane scenarios. Review these models with a local coastal engineer to understand your property's specific exposure.
Check historical flood records from county assessor and emergency management. Properties that flooded in past storms face elevated future risk.
Coastal Home Inspection: Critical Areas and Red Flags
Hire a specialized coastal home inspection evaluating salt spray damage, foundation stability, water intrusion, and structural integrity. Use inspectors with documented oceanfront experience in your region.
Coastal Property Insurance: Coverage, Costs, and Planning
Coastal property insurance operates differently than standard coverage. Standard policies often exclude water damage, including storm surge and flooding. Understand insurance requirements, costs, and coverage gaps before purchase.
Flood insurance is mandatory for high-risk properties with mortgages. Standard homeowners policies exclude flood damage. Federal flood insurance provides baseline coverage; private options may offer better coverage or pricing in some markets.
Homeowners insurance in coastal areas costs significantly more than inland equivalents. High-risk properties may face limited availability, with some insurers withdrawing from coastal markets.
Request insurance quotes before finalizing your offer. Insurance availability and cost should factor into your buying decision.
Total Cost of Ownership and Long-Term Financial Planning
When buying coastal homes in California, the purchase price represents only a portion of true ownership costs. Coastal properties generate higher ongoing expenses.
Coastal properties typically assess higher than inland equivalents due to location premiums. A $3 million oceanfront home might generate annual property taxes exceeding $30,000.
Maintenance costs run 1.5 to 2 times higher than inland properties. Salt spray accelerates deterioration of exterior elements, landscaping, and mechanical systems. Roofing, painting, and weatherproofing require more frequent attention.
Insurance costs represent a significant annual commitment. Budget for flood insurance, homeowners coverage, and potentially earthquake insurance.
Coastal HOA fees often exceed $500-800 monthly, reflecting specialized maintenance needs. Luxury communities charge substantially more.
Calculate total annual carrying costs including mortgage interest, property taxes, insurance, maintenance reserves, and HOA fees. Many coastal buyers underestimate these carrying costs and face financial strain years into ownership.
Your Next Steps: Finding the Right Coastal Home
Finding the right coastal home requires patience, local expertise, and systematic evaluation. Begin by clarifying your priorities: primary residence versus investment property, specific coastal region preference, and realistic budget including carrying costs.
Connect with a real estate professional who specializes in coastal properties and understands local market conditions, regulatory requirements, and community characteristics. Working with Rhonda Scott means accessing experience navigating coastal transactions, understanding regional market dynamics, and identifying properties that align with your long-term goals.
The coastal buying process involves more moving parts than standard residential purchases. Flood zone verification, coastal commission compliance, specialized inspections, and insurance procurement all require coordination. Professional guidance through these steps prevents costly delays and protects your interests.
Rhonda Scott has helped numerous buyers navigate buying coastal homes in California successfully. Her approach combines market knowledge with personalized attention, ensuring you understand every aspect of your coastal property investment before committing.
Buying coastal homes in California represents a significant financial and lifestyle commitment. The oceanfront location, environmental exposure, and specialized requirements demand thorough due diligence and expert guidance. Connect with Rhonda Scott to discuss your coastal property goals and develop a strategy tailored to your specific situation. With over 24 years of experience in Southern California coastal real estate and a track record of successful transactions, Rhonda brings the local insight and personalized service your coastal purchase deserves. FEMA flood mapping resources and California Coastal Commission guidelines provide official frameworks for understanding your property's regulatory environment. Start your coastal buying journey with professional guidance that prioritizes your interests and protects your investment.
Frequently Asked Questions
Is it a good time to buy a coastal home in California right now?
Timing depends on your financial readiness and long-term goals rather than short-term market cycles. Coastal markets remain competitive, but working with an experienced agent who understands local trends helps you identify opportunities aligned with your timeline and budget. Interest rates, inventory levels, and your personal circumstances matter more than waiting for a 'perfect' moment.
What extra costs should you expect when buying a coastal home?
Beyond the purchase price, budget for higher homeowners insurance premiums, potential flood insurance requirements, more frequent maintenance due to salt air and weather exposure, and possible coastal mitigation costs. Property taxes, HOA fees (common in beach communities), and specialized inspections add to the total cost of ownership. A full financial review with your advisor ensures you're prepared.
How can you check flood and erosion risks for a coastal home?
Review FEMA flood maps and local coastal hazard assessments available through county planning departments. Request a detailed flood risk report from your title company and ask about the property's elevation relative to base flood elevation. Your coastal home inspection should include erosion history and any previous flood damage. Local agents familiar with coastal regulations can identify properties in higher-risk zones.
What should you know about homeowners insurance for a coastal property?
Coastal property insurance costs significantly more than inland homes and may require separate flood coverage through the National Flood Insurance Program (NFIP) or private insurers. Carriers often impose stricter underwriting, roof age limits, and distance-from-ocean requirements. Obtain insurance quotes before closing to confirm coverage is available and affordable for your specific property and location.
Where can you find relatively affordable coastal homes in California?
Communities slightly inland from the immediate beachfront, smaller towns north of major metro areas, and properties needing renovation often offer better value than prime oceanfront locations. Mendocino County and less-developed stretches of the central coast provide alternatives to premium Orange County and Los Angeles coastal areas. Your agent's local market knowledge reveals emerging neighborhoods with growth potential.
What inspections should you get before buying a coastal property?
Beyond a standard home inspection, order a specialized coastal property inspection focusing on salt damage, foundation issues, and weather-related wear. A separate flood risk assessment and erosion evaluation are essential. Pest inspections should emphasize termite damage common in coastal climates. Your inspector should have experience with oceanfront and beachfront properties to catch issues unique to coastal environments.